
Estate Planning
Wills & Trusts
Estate Administration
Wills & Trusts
Estate Administration
The estate tax is computed based on the New York taxable estate of a resident or nonresident using the following tax table:
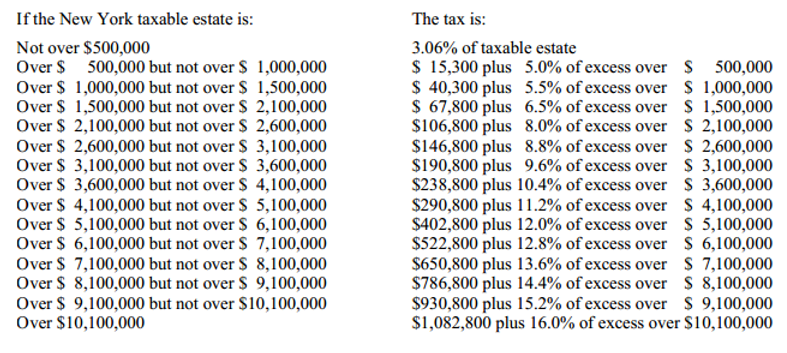
For deaths occurring from January 1 through December 31, 2026, the New York basic exclusion amount is $7,350,000. This amount is relevant to the filing requirement and the estate tax credit, but it is not a simple deduction from the value of the estate. The applicable credit is reduced when the New York taxable estate exceeds the exclusion and is eliminated at $7,717,500 (105% of the exclusion).
WARNING: The applicable credit is phased out as the New York taxable estate exceeds105% of the basic exclusion amount. See: The Cliff